Our Lendermarket review in short: version 2.0 is a licensed, low-cost P2P marketplace with a 13.46% weighted average interest rate on available loans, and you pay for that rate with patience. A late loan can wait up to 240 days for its buyback, there is no secondary market, and six of the fourteen loan originators run through Creditstar Group AS. We hold a four-figure amount ourselves and explain who the platform suits.
Lendermarket Review: The Verdict First
Our Lendermarket review ends in a qualified yes: version 2.0 works as a return-focused addition for investors who can wait, not as a place for money you might need soon. Near-zero fees and a 13.46% weighted average rate speak for it, while waits of up to 240 days before a buyback and six Creditstar lines among fourteen originators speak against it.
Lendermarket suits you if you already know how P2P lending works and can leave money invested for months. You steer it yourself: you pick regulated or unregulated loans and decide how much Creditstar exposure to accept.
Skip it if you may need the money at short notice. The same applies if you expect deposit-style protection, because no deposit guarantee scheme or investor compensation scheme covers these investments.
We have a four-figure amount invested on Lendermarket ourselves. Every part of this verdict is backed below. The evidence comes from Lendermarket's own figures, the 2025 annual reports of Lendermarket and Creditstar, and the official buyback table.
Sign up through our link and the referral is stored in the background, no promo code needed
Watch Our Lendermarket Review
We walk through the same verdict, the two services and the buyback timing on camera.
Who Is Behind Lendermarket?
Lendermarket is run by Lendermarket Limited, an Irish company with its registered office in Dublin and company number 585178. It was established in 2018 and has an operational presence in Tallinn, Estonia.
The licence. Since 17 December 2024, the Central Bank of Ireland has authorised Lendermarket as a European Crowdfunding Service Provider under Regulation (EU) 2020/1503. Its entry in the Central Bank of Ireland register carries reference C513967 and shows no withdrawal. The authorisation comes with passporting, which is a right of the provider: Lendermarket can offer its regulated service in other member states without a separate licence in each. Your own eligibility is a separate matter. You need to be at least 18, hold a bank account in the EEA or Switzerland and be tax resident in the EU or Switzerland. Private and business accounts are both possible, and the platform accepts euros only.
The owner. Who owns Lendermarket? Its 2025 annual report names SA Financial Investments OÜ, registered in Estonia, as parent company and ultimate parent undertaking. Creditstar Group's 2025 annual report names the same company as sole shareholder of Creditstar Group AS, with 100%. Lendermarket and Creditstar Group are therefore sister companies under one parent.
That link reaches straight into the loan list. Six of the fourteen loan originators on the platform are Creditstar lines. Lendermarket's own report describes the company as "part of a broader corporate structure in which Creditstar Group is also an important platform participant and group buyback undertaking provider". It adds that "certain Loan Originators may be related parties".
What stands out is where all this is written down: in the audited annual reports of both companies. For your portfolio, the consequence is plain. Spreading money across the Creditstar lines does not spread it across unrelated companies.
The people. The About page lists Carles Federico as CEO, Aldar Tsybikov as Head of Finance and Helari Laurent as CTO.
Verify your identity via Sumsub, then invest from €10 per loan with a private or business account
Lendermarket in Numbers
Lendermarket publishes its platform statistics openly, and the key figures sit in the table below. Two of them need context first.
The 13.46% is the weighted average interest rate of the loans available right now. It is not a net return. Lendermarket's own footnote says your portfolio returns can be higher or lower and that past performance does not guarantee future returns, while its marketing speaks of up to 15% APY.
One thing to flag is the 0% default rate. Late loans that an originator later buys back do not count as defaults, so the figure says nothing about how long you wait. The platform's portfolio health data shows roughly one euro in ten of outstanding capital running late or pending at a given moment. Read every figure here as a snapshot: past performance is not a reliable indicator of future performance.
Lendermarket | |
|---|---|
| Licence | ECSP authorisation from the Central Bank of Ireland, reference C513967 |
| Total invested | More than €689 million since launch |
| Interest earned | About €44.7 million earned by investors since launch |
| Active portfolio | Around €62 million |
| Registered investors | More than 31,000 |
| Loans available | Several thousand |
| Weighted avg. rate | 13.46% on available loans, an interest rate rather than a net return |
| Reported default rate | 0%, with bought-back late loans not counted as defaults |
| Loan originators | 14, of which 7 regulated and 7 unregulated |
| Minimum per loan | €10, no maximum |
| Minimum withdrawal | €50 |
| Secondary market | Not offered, Auto Invest FLEX provides a conditional exit |
| Who can invest | 18+, bank account in the EEA or Switzerland, tax residency in the EU or Switzerland |
| Currency | Euros only |
Tip: scroll horizontally to see all columns
Two Services: Regulated and Unregulated Loans
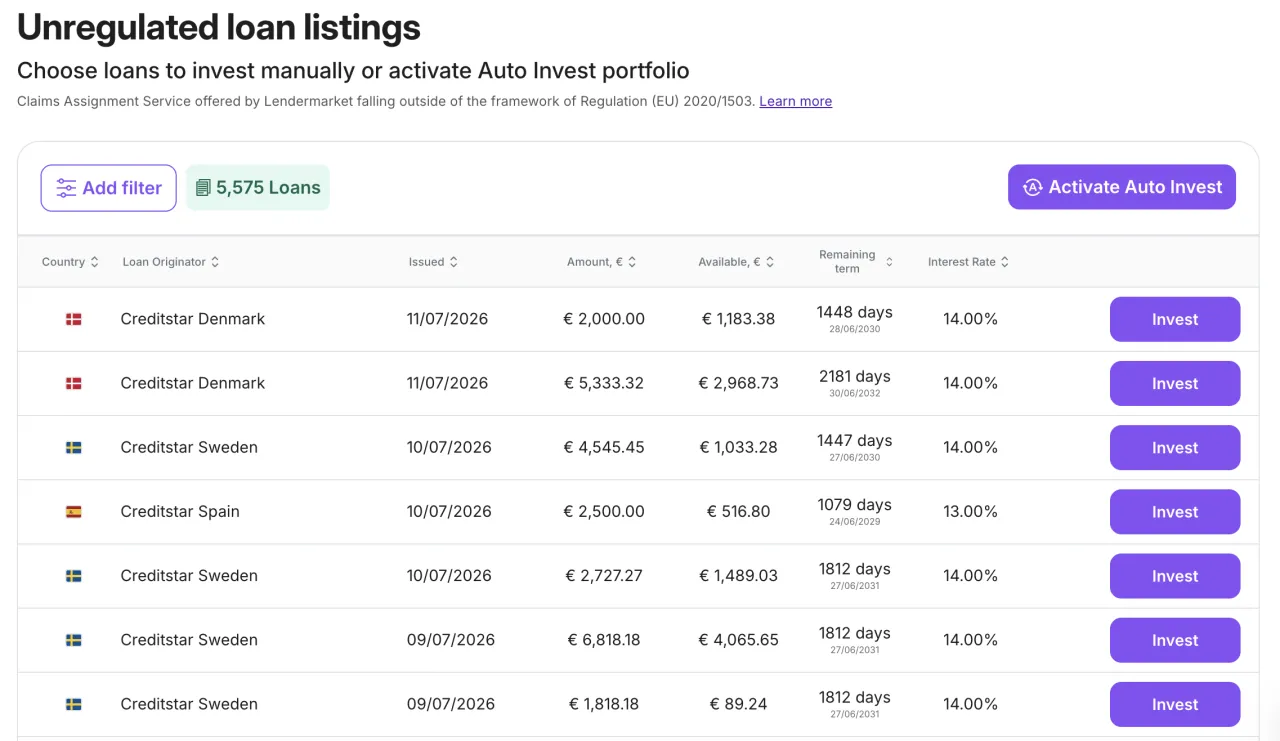
Lendermarket runs two services side by side, and every loan shows which one it belongs to. The screenshot shows the unregulated listing page, with the service note right under the heading.
The Crowdfunding Service is regulated under Regulation (EU) 2020/1503. Here you lend to the loan originator under a Limited Recourse Loan or a Limited Purpose Loan agreement. Seven originators work on this side: RapiCredit (Colombia), RapiCredit Iberica (Spain), Dineo (Spain), Gatelink (Estonia), Flowpay (Czech Republic), OK Credit (Moldova) and Best Credit (Romania).
The Claims Assignment Service falls outside that regulation. Here you acquire claims through an assignment agreement. This side carries Credifiel (Mexico) and six Creditstar lines: Spain, Finland, Denmark, Czech, Sweden and Monefit (Estonia). That Monefit line is a Creditstar lending line, not the Monefit SmartSaver investment product. In both services, the originator owes you the money, not Lendermarket.
The labelling works well and keeps the structure transparent. The regulated side follows the EU crowdfunding rules, including a Key Investment Information Sheet per project. On top of that, Lendermarket assesses your knowledge and experience, and non-sophisticated investors get a four-day cooling-off period to cancel an investment without penalty.
That said, regulated does not mean protected against loss. Neither service is covered by deposit guarantee schemes under Directive 2014/49/EU or by investor compensation schemes under Directive 97/9/EC.
One detail is easy to miss. Gatelink is a separate company, licensed in Estonia and without a group guarantee, yet it lends to Creditstar companies. Its regulated loans are even listed with the identifier Creditstar Finland, the Creditstar company on the other side of those loans. That makes Gatelink a seventh line leading back to Creditstar, on top of the six Creditstar lines, so picking only regulated loans does not cut every tie to the group.
Buyback and Extensions: How Long You May Wait
The buyback guarantee is the backstop for late loans, and its timing matters more than its name. Lendermarket's marketing pages shorten it to 60 days. The official extensions page gives the full rule: "The Buyback Guarantee activates 60 days after the final scheduled or extended maturity date." The maximum number of late days is the maximum extension plus those 60 days.
In practice, the originator sets the pace. Due dates can change within its extension policy, which Lendermarket shows under every loan, and the 60-day countdown only starts after the final, possibly extended, maturity date. The originator then buys the loan back at the outstanding principal plus accrued interest. Lendermarket is candid about the limit: "A Buyback Guarantee is a contractual obligation of the Loan Originator and is dependent on their financial capacity."
Take a Creditstar loan whose final payment falls due on 1 March. With the full 180 days of extensions plus 60 days, the buyback only activates on 27 October. The table shows the chain for every originator; the six Creditstar lines are Spain, Finland, Denmark, Czech, Sweden and Monefit. OK Credit and Best Credit are not listed in the extension table.
Two more details help when you compare originators. Originators keep 5% to 10% of each loan as skin in the game. Lendermarket also publishes a quarterly risk score per originator and states that it is not a credit rating under Regulation (EC) No 1060/2009. The group guarantee, the 2025 accounts and the portfolio data get their full treatment in our layer-by-layer Lendermarket safety check.
Max. extension | Buyback after | Worst case | |
|---|---|---|---|
| Creditstar (6 lines) | 180 days | 60 days | Up to 240 days late |
| Credifiel | 180 days | 60 days | Up to 240 days late |
| Dineo | 60 days | 60 days | Up to 120 days late |
| RapiCredit | 0 days | 60 days | Up to 60 days late |
| RapiCredit Iberica | 0 days | 60 days | Up to 60 days late |
| Gatelink | 0 days | 60 days | Up to 60 days late |
| Flowpay | 0 days | 60 days | Up to 60 days late |
| OK Credit, Best Credit | Not listed | Not listed | Not listed |
Tip: scroll horizontally to see all columns
Auto Invest and Auto Invest FLEX
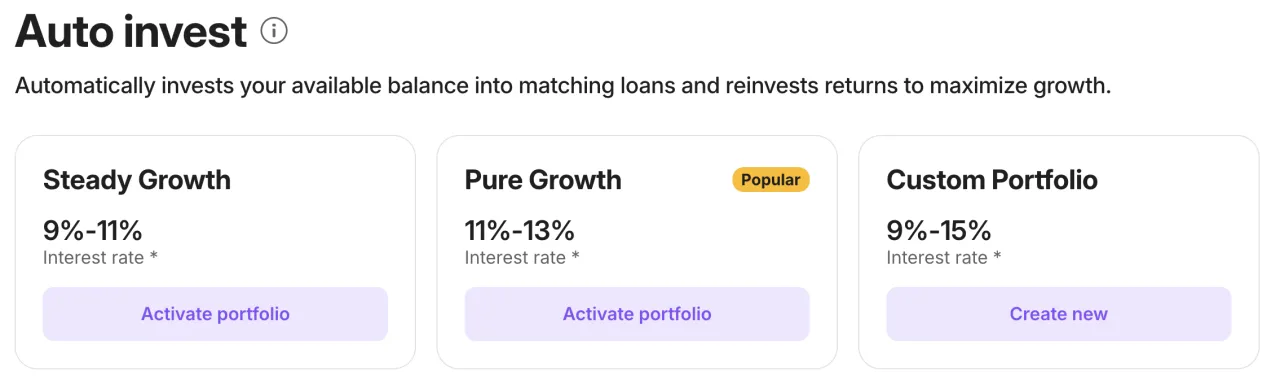
Auto Invest places your available balance into loans that match your settings, and the interface says it reinvests returns as well. Three starting points sit on the screen: Steady Growth at a 9% to 11% interest rate, Pure Growth at 11% to 13%, and a Custom Portfolio, which the interface shows at 9% to 15%.
Setting one up is easy to follow. The flow runs through deposit, amount, period, service type and activation. Beyond that, you can filter by originator and more. Give the service type step your full attention. Lendermarket also asks during onboarding whether you want to invest in regulated or unregulated services, and you can review that choice in your account settings at any time, so check both places before money goes out. The settings traps beginners fall into are covered in our guide to five Lendermarket beginner mistakes.
Lendermarket does not offer a secondary market, and Auto Invest FLEX fills part of that gap. The platform advertises FLEX with target returns of up to 10.5%, which sits below the 13.46% average rate on available loans. You can request an exit of 10%, 25%, 50%, 75% or 100% of your current value. The fee is 3.5% of the exited amount, so taking out €1,000 costs €35 and leaves you €965. Under the FLEX terms, processing takes up to 10 calendar days.
The exit only goes through if replacement funding is found. Without it, the request lapses at no cost and your investment keeps running. Lendermarket describes FLEX as "conditional only" and says it "does not constitute a guaranteed right to liquidity". It is not a sale between investors either. After an approved exit, reinvestment into that portfolio pauses for 10 business days. Because loans are bought back in whole units, the executed exit can be larger than requested: so you may end up exiting a little more than you asked for.
The trade-off is clear. FLEX gives you a door out, at a price and without a promise. For a platform with no secondary market, that is a workable compromise.
Choose Steady Growth, Pure Growth or your own filters, service type included
Fees: Close to Zero, With Three Exceptions
Lendermarket scores well on costs, and its fee list is short and straightforward. Registration, investing and portfolio management cost nothing. SEPA bank deposits are free too, while SWIFT transfers are not accepted.
Three charges remain:
- •Extra bank withdrawals: the first one in each calendar month is free, and every further one in the same month costs €2, according to the Help Centre.
- •Card payments: card deposits and card withdrawals may carry a processing fee, and for card withdrawals Lendermarket shows it before you confirm.
- •FLEX early exit: 3.5% of the amount you take out.
The one caveat concerns the fee page itself. It shows bank withdrawals as free, marked with an asterisk, and we found no mention of the €2 rule there. That makes the charge a minor drawback: one withdrawal a month stays free, and bank withdrawals usually arrive within 3 business days. The minimum withdrawal is €50, and below that you can only take out your full balance.
Lendermarket also deducts no tax at source. Repayments reach your bank account "without any deduction or withholding". You download a tax report from your account and declare the income under your own country's rules.
Lendermarket Pros and Cons
Both lists condense the review so far. Start with What to watch, because a single point there can be reason enough to pass on the platform.
What works
- ECSP authorisation from the Central Bank of Ireland since 17 December 2024
- Every loan labelled regulated or unregulated, with a service type filter in Auto Invest
- 13.46% weighted average interest rate on available loans
- No fees for registration, investing or portfolio management, plus one free bank withdrawal a month
- Originators keep 5% to 10% of each loan as skin in the game
- Ownership and group links disclosed in the 2025 annual reports of Lendermarket and Creditstar
What to watch
- On the Creditstar lines and Credifiel, a late loan can wait up to 240 days for its buyback
- Six of the fourteen originators run through Creditstar Group AS
- No secondary market, and FLEX exits cost 3.5% and depend on replacement funding
- No deposit guarantee or investor compensation scheme
- The platform company lost €1.12 million in 2025, and its auditors flagged a material uncertainty on going concern
- Version 2.0 has only been live since April 2024
- Investing works in euros only
From Lendermarket 1.0 to 2.0
Lendermarket's history has one difficult chapter. From 2022 to 2024, the platform ran into payment delays, known as pending payments. The About page addresses them directly: "The payment delays were a difficult period, but we resolved all obligations in full with interest."
Lendermarket 2.0 launched in April 2024, and the 1.0 platform closed on 31 December 2025. Today's version comes across as a well-structured product: licensed since December 2024, labelled by service and open about the buyback chain for 12 of its 14 originators.
The company behind it lost €1,123,349 in 2025, up from €299,639 in 2024, with accumulated losses of €2,609,424. Its auditors added an emphasis of matter on a material uncertainty related to going concern. Continuation depends on profitable trading and on "ongoing financial support from group companies". Your loans are owed by the originators, not by Lendermarket. A platform that leans on group funding is still a risk worth weighing, and our safety analysis of Lendermarket goes through those accounts in detail.
On Trustpilot, Lendermarket holds 4.1 out of 5 from 744 reviews, 63 of them from the last 12 months. The spread leaves a split impression: 45% five stars, 12% four, 7% three, 4% two and 32% one star. Lendermarket replies to negative reviews.
Filter by service type and originator from €10 per loan, and set your Creditstar share yourself
Our Verdict on Lendermarket 2.0
Lendermarket 2.0 holds up on the points you can check yourself. The licence is on public record, the fees are close to zero, both annual reports disclose the ownership, and the buyback chain is published for 12 of the 14 originators. What the platform does not offer is speed: there is no secondary market, FLEX exits are conditional, and Creditstar loans can run up to 240 days late before a buyback.
The deciding factor is how you use it. Lendermarket fits investors who treat P2P as one part of a wider portfolio, choose originators and service type deliberately, and can leave money untouched for months. It does not fit an emergency fund, a need for deposit-style protection or a wish to avoid heavy exposure to one lending group. Lendermarket's own risk statement advises not to invest more than 10% of your net worth in crowdfunding projects. We are not financial advisers, and this is not investment advice.
Here is how we handle it ourselves. We started with a smaller amount, now hold a four-figure sum and plan to expand step by step. So far, our experience has been positive. Before your first deposit, work through our 10 things to know before investing in Lendermarket. Switching on the two-factor authentication that Lendermarket recommends is a sensible first setting.
If you are new to Lendermarket, signing up through our link brings 1.5% cashback. It applies to your net invested funds during the first 90 days after your account is validated. The cashback is credited to your Lendermarket account within 5 business days after that period ends, with no code to type in. Our Lendermarket bonus guide explains the conditions. Weighing Lendermarket against Monefit SmartSaver, the Creditstar Group's own investment platform? Our Lendermarket vs Monefit SmartSaver comparison puts the two side by side.
Paid on the net invested funds of new investors, credited within 5 business days after the period, no code to type in
P2P-Kredite im direkten Vergleich
Wie schlägt sich diese Plattform gegen Mintos, Bondora, Debitum und Co.? In unserem P2P-Kredite Vergleich stehen 9 Plattformen nach Rendite, Regulierung, Rückkauf und Risiko nebeneinander.
Frequently asked questions
You might also like
Is Lendermarket Safe? Licence, Buyback and the Creditstar Link
The licence, buyback chains of up to 240 days, the Creditstar ownership link and the 2025 accounts, checked layer by layer.
Lendermarket vs Monefit SmartSaver 2026: 13.46% or 7.50%?
Returns, liquidity, regulation and fees compared, plus the Creditstar link both platforms share.
Lendermarket Bonus 2026: 1.5% Cashback Without a Promo Code
How the 1.5% cashback via our link activates, when it pays out and how it differs from the €75 refer-a-friend offer.
Legal information
The content on this site has been researched carefully. Our sources are the providers' publicly available information and their terms and conditions. Despite regular checks we cannot warrant that the data is current, accurate or complete. Binding information on products and prices is only available on each provider's own website. Unless stated otherwise, the conditions shown apply to new customers.
Not financial advice
Our content is informational and comparative only. It is not financial, tax or legal advice, and it is neither a recommendation to buy nor an invitation to take out a financial product. Make your decisions based on your own situation and risk tolerance, and consult an independent adviser if you need one.
Risk warning
Every investment carries risk. Values can rise or fall, and past performance does not indicate future returns. You can lose part or all of the capital you invest. Crypto-assets are largely unregulated, are not covered by deposit guarantee or investor compensation schemes, and carry a high risk of total loss.
Advertising and affiliate links
Some links on this site are marked with an asterisk (*) and are affiliate links (advertising). If you take out a product through one of these links, we receive a commission from the provider at no additional cost to you. That is how you support our work.